Prestige Insurance Claims Adjuster logoPrestige Insurance Claims Adjuster
Fast, upfront public adjuster in St. Petersburg, FL, free quote in minutes

Public Adjuster St. Petersburg

A public adjuster St. Petersburg homeowners hire represents the policyholder while a company adjuster represents the insurer, and that difference decides who builds the loss estimate.
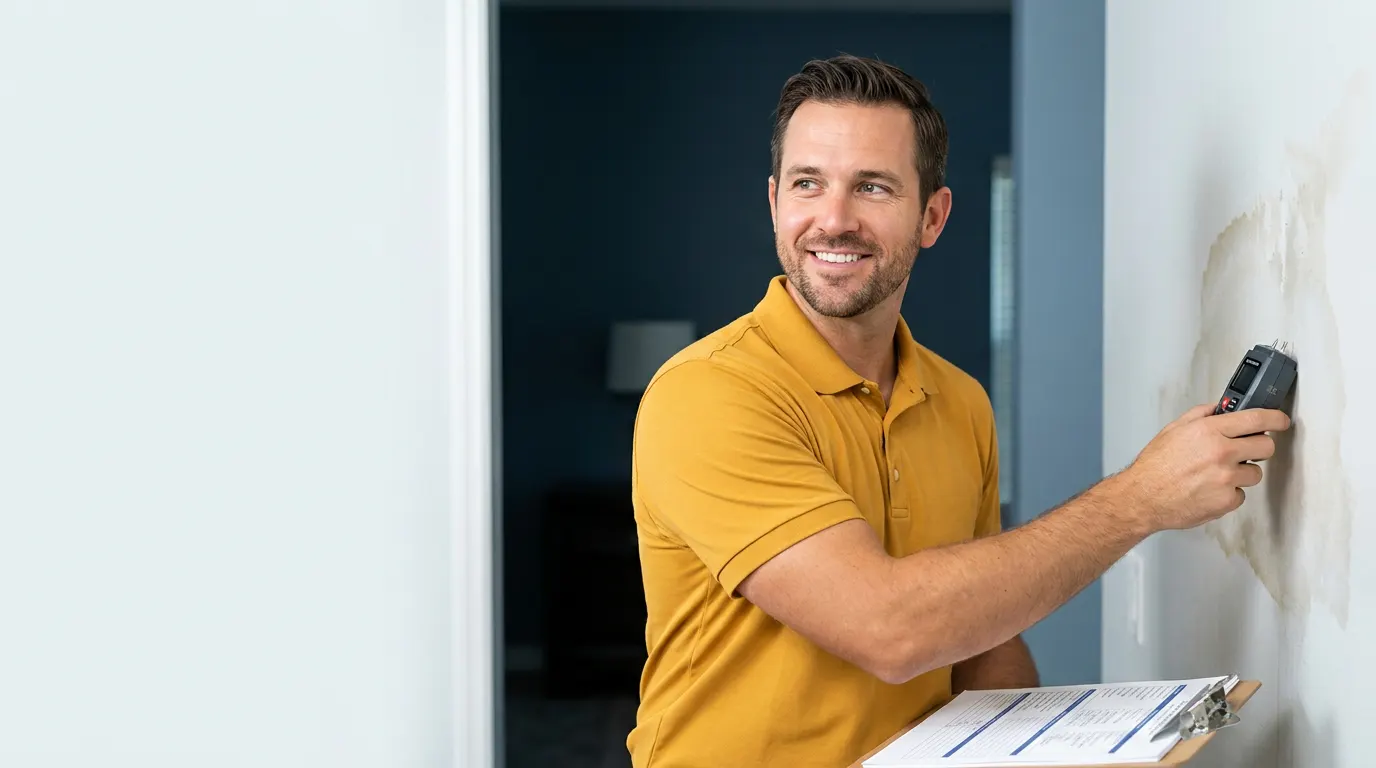
Get your free public adjuster quote, St. Petersburg

We only use your ZIP to check availability, no spam.

Hurricane & Windstorm ClaimsRoof Damage ClaimsWater & Plumbing Damage Claims
Public Adjuster in St. Petersburg, FL
Public Adjusterin St. Petersburg, FL

What is Public Adjuster in St. Petersburg, FL?

A public adjuster in St. Petersburg is a Florida-licensed insurance claim professional who works for the policyholder, not the insurer, to document a property loss and negotiate the settlement paid under the homeowner's or commercial policy.

Why homeowners choose Prestige Insurance Claims Adjuster

  • ✓Florida law caps public adjuster fees at 10% of the claim payment for a declared-emergency claim during the first year, and 20% on standard non-emergency claims, under Florida Statute 626.854.
  • ✓A public adjuster works for the policyholder; the insurance company's adjuster works for the insurer, so the two build separate damage estimates.
  • ✓Prestige Insurance Claims Adjuster handles storm, wind, water, fire, roof and mold-related property claims for homes and small commercial buildings in St. Petersburg and Pinellas County.
  • ✓Most fee agreements are contingency-based, meaning payment comes as a percentage of what the claim recovers, not an upfront charge.
Hurricane & Windstorm Claims
Roof Damage Claims
Water & Plumbing Damage Claims
Our Expertise

Public Adjuster services we provide

Every service reflects the same meticulous attention to detail, whether it's a single job or a larger public adjuster project across St. Petersburg.
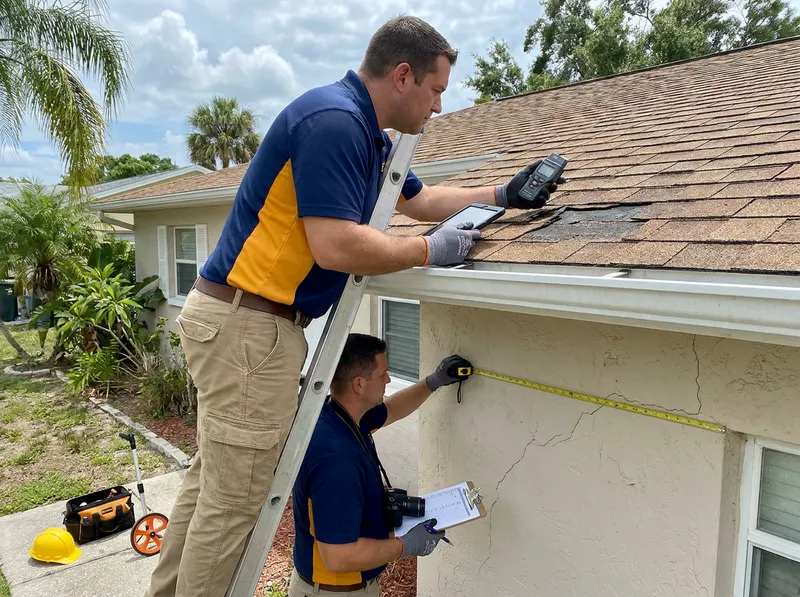
Hurricane & Windstorm Claims in St. Petersburg, FL

Hurricane & Windstorm Claims

Wind and hurricane losses are the dominant St. Petersburg claim type, tied to Atlantic season landfalls from June through November. Documentation covers roof uplift, wind-driven rain intrusion, soffit and fascia damage, and screen enclosure loss common on Coquina Key and Bahama Shores waterfront lots.

Get a quote →
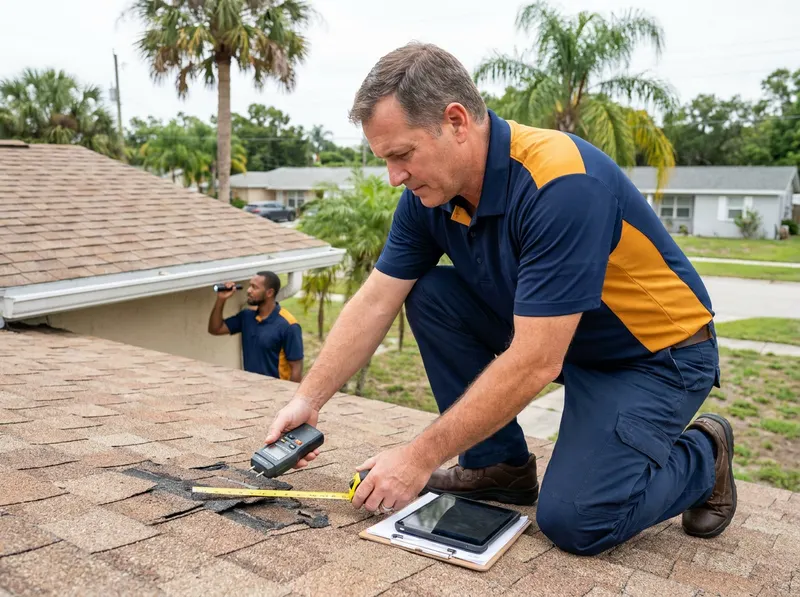
Roof Damage Claims in St. Petersburg, FL

Roof Damage Claims

Roof claims turn on age, wind rating and the difference between repair and full replacement. Evidence includes drone imagery, moisture readings and matching-shingle analysis, which matters when an insurer offers a partial patch on a roof that Florida code may require replaced.

Get a quote →
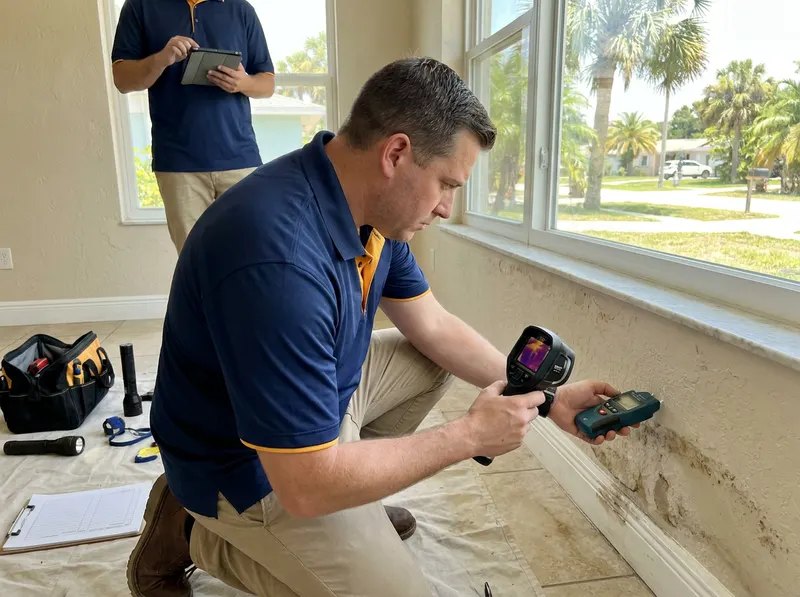
Water & Plumbing Damage Claims in St. Petersburg, FL

Water & Plumbing Damage Claims

Water losses from burst supply lines, roof leaks and appliance failures drive steady off-season demand. Because insurers often dispute whether damage is 'sudden and accidental' versus long-term seepage, the file documents source, timeline and moisture mapping behind walls and under flooring.

Get a quote →
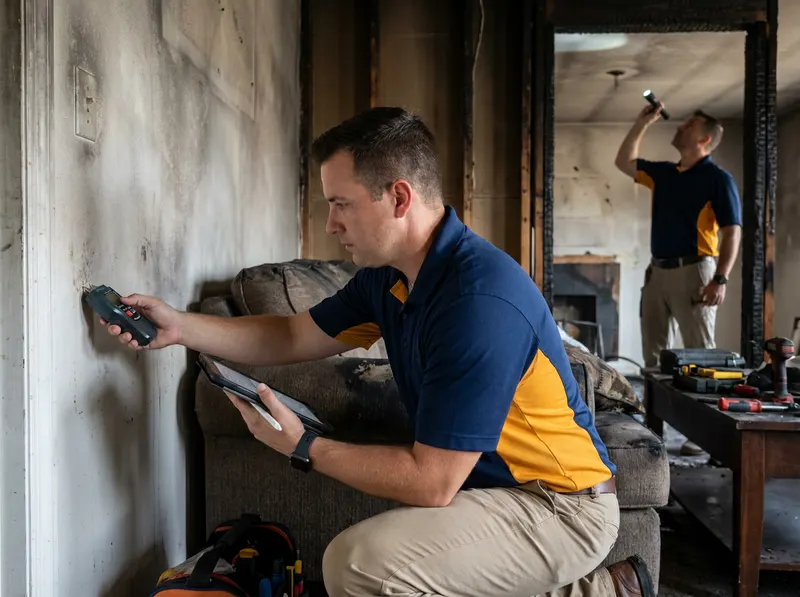
Fire & Smoke Damage Claims in St. Petersburg, FL

Fire & Smoke Damage Claims

Fire claims include structural burn damage plus smoke, soot and water-from-suppression losses that insurers frequently undercount. The estimate separates cleanable contents from total losses and accounts for smoke penetration into HVAC and drywall.

Get a quote →
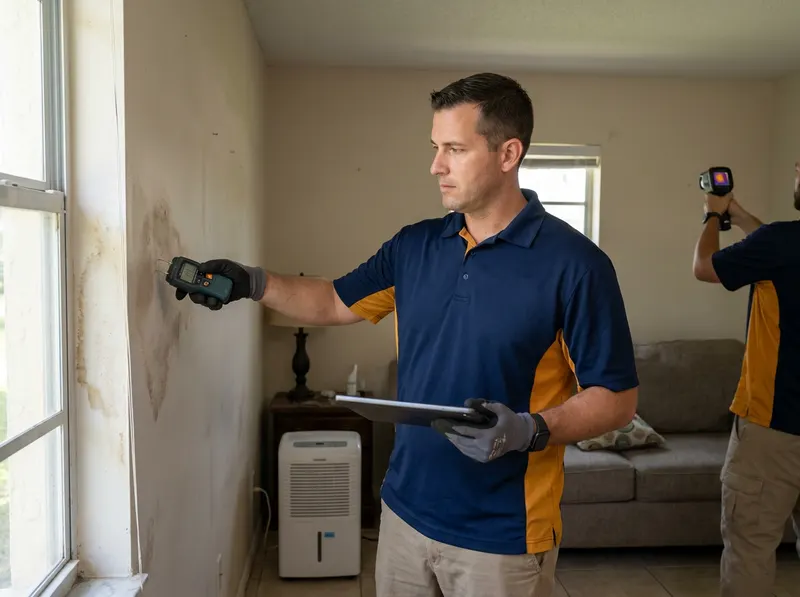
Mold & Humidity Damage Claims in St. Petersburg, FL

Mold & Humidity Damage Claims

Mold claims hinge on Florida's policy sub-limits, often capped at $10,000, and on proving the mold traces to a covered water event. Documentation ties the growth to the originating leak so it is not written off as maintenance.

Get a quote →
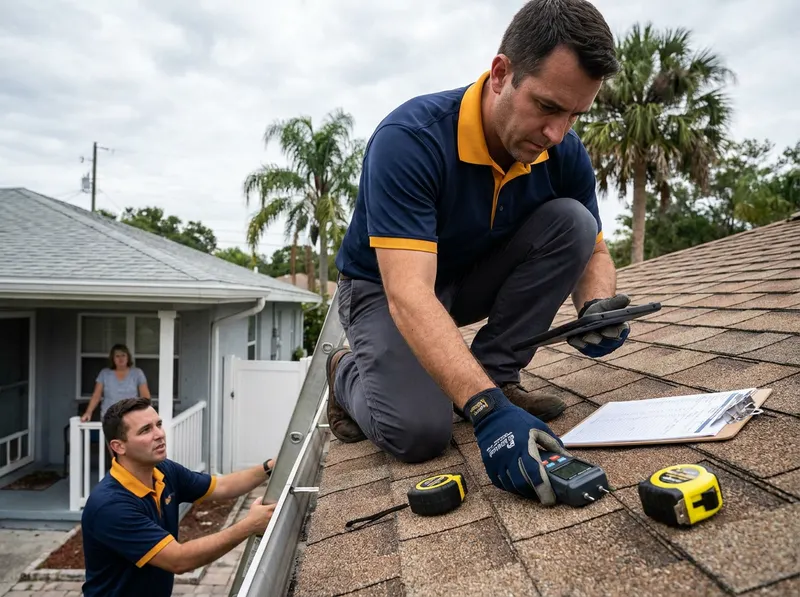
Denied & Underpaid Claim Reopening in St. Petersburg, FL

Denied & Underpaid Claim Reopening

A denied or lowballed claim can be reopened with new documentation without filing a lawsuit. Florida allows policyholders to dispute a decision, and a rebuilt estimate with photos, code citations and contractor bids is the core of that dispute.

Get a quote →
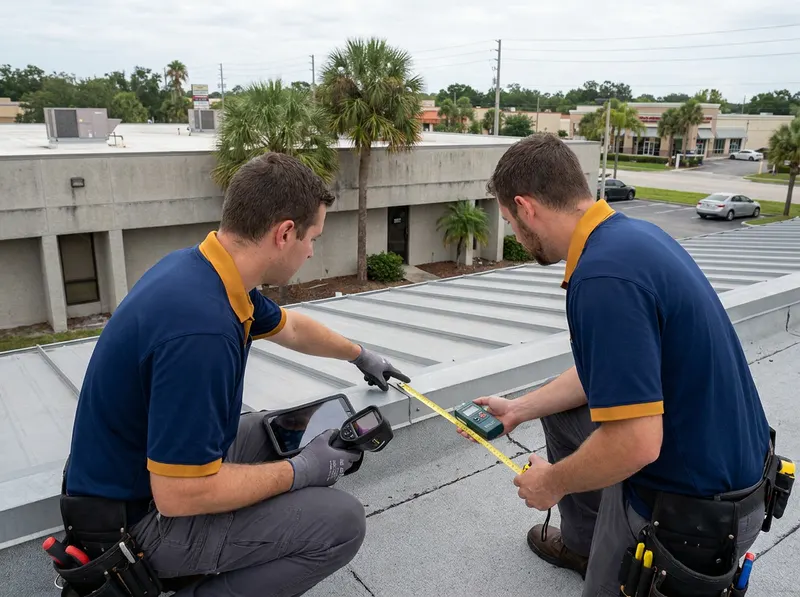
Commercial Property Claims in St. Petersburg, FL

Commercial Property Claims

Small commercial buildings, from Kenwood storefronts to office units, carry business-personal-property and loss-of-use coverage most owners never fully claim. The file separates building damage, contents and income impact under the applicable policy.

Get a quote →
The essentials

What St. Petersburg customers should know

  • Florida law caps public adjuster fees at 10% of the claim payment for a declared-emergency claim during the first year, and 20% on standard non-emergency claims, under Florida Statute 626.854.
  • A public adjuster works for the policyholder; the insurance company's adjuster works for the insurer, so the two build separate damage estimates.
  • Prestige Insurance Claims Adjuster handles storm, wind, water, fire, roof and mold-related property claims for homes and small commercial buildings in St. Petersburg and Pinellas County.
  • Most fee agreements are contingency-based, meaning payment comes as a percentage of what the claim recovers, not an upfront charge.
  • Claim demand in St. Petersburg peaks during Atlantic hurricane season, June 1 through November 30, with sharp spikes right after a named storm tracks through Tampa Bay.
The Prestige Insurance Claims Adjuster standard

Why St. Petersburg keeps calling us back

01

A clear, written price

You get a firm, itemized quote for your public adjuster before any work begins, no surprises, no pressure.

02

Your property, protected

Careful prep, tidy work, and a full cleanup when we are done. We treat your home and belongings like our own.

03

One crew, start to finish

The same trusted, background-checked team from the first call to the final check.

Buyer's guide

Choosing the right public adjuster pro

If your insurer's payout roughly matches your repair bids and the claim is moving, you can often manage a small first-party claim yourself and skip an adjuster fee. If the offer is thousands short of your contractor estimates, the claim has stalled past Florida's 90-day payment deadline, or the loss is complex, such as hidden water intrusion behind Shore Acres drywall or a wind-lifted roof in Snell Isle, a licensed public adjuster builds the documented counter-estimate. If the insurer has denied the claim outright, the practical choice narrows to a public adjuster reopening the file or an attorney filing suit; a public adjuster is the non-litigation route and costs a capped percentage instead of legal fees.

The trade-off is straightforward: representation costs a share of the recovery, so it earns its keep only when the documented loss meaningfully exceeds the current offer.

Investment

Public Adjuster cost and what drives it

Every project gets a firm, written price after a free on-site visit. Ranges below for orientation.

Declared-emergency claim fee (first year), per FL Statute 626.854up to 10% of claim payment
Standard non-emergency claim fee capup to 20% of claim payment
Initial policy review & loss inspectiontypically no upfront cost (contingency)
Reopening an underpaid or denied claimcontingency % of additional recovery only
Small commercial property claimquoted on scope, within statutory caps
Free, no-pressure estimate

Get it done right

Tell us about your public adjuster job and we'll send a clear, written quote, usually the same day. Or just call and talk to a real St. Petersburg pro.

(727) 339-7580
Get your free public adjuster quote, St. Petersburg

We only use your ZIP to check availability, no spam.

Where we work

Areas we serve near St. Petersburg

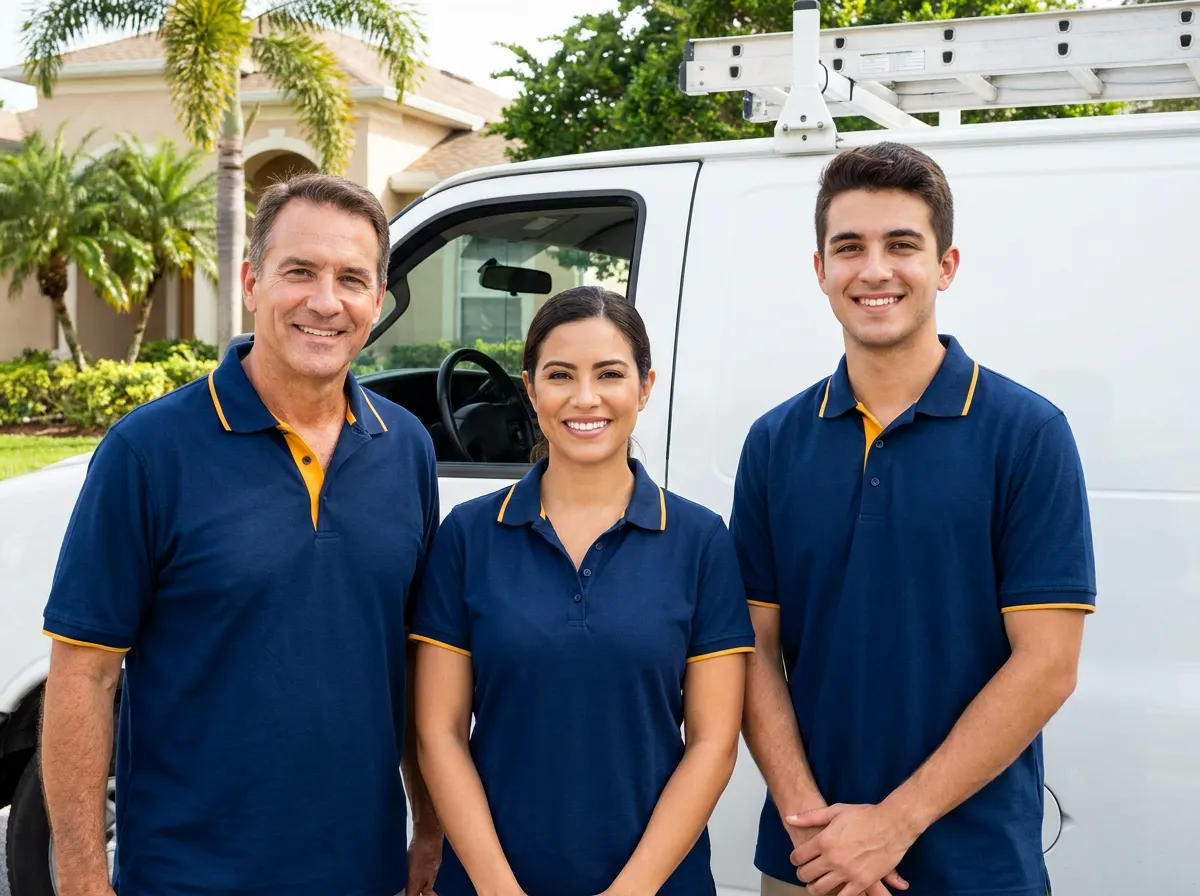
Prestige Insurance Claims Adjuster public adjuster team in St. Petersburg, FL

St. Petersburg sits on a low peninsula between Tampa Bay and the Gulf, and its waterfront pockets, Shore Acres, Coquina Key, Bahama Shores and Broadwater near Gulfport, flood and take storm surge in ways inland Allendale Terrace or Kenwood rarely see, which is why identical-looking policies pay out very differently after the same storm. Historic Roser Park and Old Northeast add another wrinkle: older masonry and wood-frame homes near the Pier District and Vinoy Park often need code-upgrade coverage the insurer's first estimate skips. Prestige Insurance Claims Adjuster documents claims to Pinellas County conditions rather than a generic template.

Old NortheastKenwoodSnell IsleShore AcresHistoric Roser ParkCrescent LakeCoquina KeyBroadwaterAllendale TerraceBahama Shores
Questions

Common questions

How much does a public adjuster cost in St. Petersburg, FL?
Florida caps public adjuster fees by law. Under Florida Statute 626.854, the fee cannot exceed 10% of the claim payment on a declared-emergency claim during the first year after the event, and 20% on standard non-emergency claims. Fees are contingency-based, so a St. Petersburg policyholder pays a percentage of what the claim recovers rather than an upfront charge. Details on Florida's rules for insurance professionals are published by the Florida Department of Financial Services at myfloridacfo.com.
Can't I just handle my St. Petersburg insurance claim myself?
Yes, and for a small, clearly-covered loss where the insurer's offer matches your repair bids, handling it yourself avoids any fee. The reason many St. Petersburg homeowners bring in a public adjuster is a gap: the payout falls thousands below contractor estimates, or the claim stalls past Florida's 90-day payment deadline described at floir.com. A public adjuster builds the documented counter-estimate the insurer's adjuster did not.
How do I know a St. Petersburg public adjuster is licensed and legitimate?
Every public adjuster operating in St. Petersburg must hold an active Florida all-lines or public adjuster license, verifiable through the Florida Department of Financial Services licensee search. A legitimate adjuster gives you a written statutory fee agreement before starting and never asks you to sign a repair contract. The National Association of Public Insurance Adjusters at napia.com outlines the professional standards these adjusters follow.
When should St. Petersburg homeowners line up a public adjuster before hurricane season?
The practical window is spring, April and May, before Atlantic hurricane season opens June 1. Adjusters are booked solid in the days after a named storm tracks through Tampa Bay, so reviewing your policy and identifying an adjuster early means faster documentation if a Shore Acres or Snell Isle roof takes wind damage. The National Hurricane Center at nhc.noaa.gov publishes the seasonal outlook homeowners use to prepare, and FEMA's flood guidance at fema.gov helps separate wind coverage from flood coverage.
What kinds of property losses does Prestige Insurance Claims Adjuster handle in St. Petersburg?
Prestige Insurance Claims Adjuster handles storm and wind, roof, water and plumbing, fire and smoke, mold, and denied or underpaid claims for homes and small commercial buildings across St. Petersburg and Pinellas County. Roof and water losses drive steady year-round demand, while wind claims spike after storms. Florida building code requirements, referenced at floridabuilding.org, often trigger replacement rather than repair, and matching-material issues follow guidance recognized under the state's Unfair Insurance Trade Practices Act; the Insurance Information Institute at iii.org explains how these coverages interact.

Get started today

Free estimates for St. Petersburg & the surrounding area.
public adjuster guides

How much does a public adjuster charge in St. Petersburg?, Pricing Guide →What percentage do public adjusters take on a hurricane claim in St. Petersburg?, Pricing Guide →Can a public adjuster reopen a denied insurance claim in St. Petersburg?, Complete Guide →Public Adjuster for a St. Petersburg Roof Damage Claim →